Namibian employers have been urged to review salaries against market rates and the rising cost of living, amid concerns that inadequate remuneration and weak employee benefits are contributing to financial stress and growing dependence on debt among workers.
Portfolio Manager Klestina Kauhondamwa, CA and CAIA, said employers should not wait until workers become dissatisfied or labour disputes arise before reviewing compensation, warning that poor remuneration practices could undermine employee financial stability and workplace productivity.
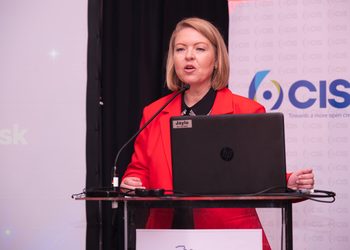
Speaking at the Institute of People Management (IPM) Namibia Annual Conference 2026, Kauhondamwa said financial wellness was not determined by income alone but also by employees’ ability to meet financial obligations, manage debt and withstand unexpected expenses.
She said companies needed to ensure that salaries reflected prevailing market conditions and that employees received fair compensation for their work.
“If a company genuinely has a budget for the role, we need to get to a point where we start to pay people market rates, because it is just a matter of time before that person realises something is wrong here,” Kauhondamwa said.
She warned that employees could remain financially vulnerable despite being formally employed, particularly where salaries were insufficient to cover household expenses and employee benefits offered limited protection against unexpected financial shocks.
Kauhondamwa said employers should also address payroll inconsistencies, including delayed salaries, unexplained deductions, late reimbursement of work-related expenses and unclear bonus arrangements.
She said workers typically planned their monthly financial commitments around expected salary payment dates, meaning delays could force them to rely on overdrafts, short-term loans or credit cards to meet their obligations.
“If you have been paid for a long time, you get used to it and you budget for the money before the money even comes in. So, if it does not come when you expect it, it is really frustrating,” she said.
Kauhondamwa said companies should establish transparent compensation policies, communicate payroll deductions clearly and ensure that agreed payments were made on time.
She also criticised inconsistent performance targets and unclear bonus eligibility requirements, saying such practices created uncertainty for employees who depended on additional earnings to meet financial commitments.
Beyond salaries, Kauhondamwa called for stronger employee benefits, including medical aid, group life insurance, income protection and retirement savings arrangements.
She said employers needed to assess whether existing benefits were affordable and adequately protected workers, particularly lower-income employees who might struggle to pay for comprehensive medical cover.
Inadequate medical benefits, she warned, could expose workers to unexpected healthcare expenses and additional financial pressure.
Kauhondamwa also raised concerns about employees reaching retirement without sufficient savings, urging companies to strengthen retirement planning and provide workers with guidance on managing their long-term financial security.
She said employers should encourage participation in pension schemes and help employees understand the financial implications of retirement decisions.
The portfolio manager further called on human resources departments to pay closer attention to employees who repeatedly requested salary advances, saying such requests could indicate deeper financial difficulties.
She said workers might be struggling with debt, medical expenses or family obligations, requiring employers to understand the underlying causes rather than simply processing or rejecting requests.
Kauhondamwa also cautioned against workplace financial education programmes that exposed financially vulnerable employees to unsuitable financial products.
“You need to make sure that in your attempt to build capacity, you are also asking who you invite, so that you do not end up leaving your workforce worse off,” she said.
She urged employers to provide independent financial education covering budgeting, debt management, savings and employee benefits, while ensuring that advice was relevant to workers’ financial circumstances.
However, she stressed that financial education alone would not resolve employees’ financial difficulties if companies continued to operate unreliable payroll systems or maintained inadequate compensation practices.
Kauhondamwa said employers should regularly review internal processes and employee feedback to determine whether workplace policies were contributing to financial stress.
“If you realise that the salaries are always delayed and you figure out there are errors in the processes, or there are delays, are you actually checking with the finance team to make sure that the payment process is smooth and efficient for everyone?” she asked.
She said financial wellness should ultimately be measured by employees’ ability to manage their finances, absorb unexpected expenses and make financial decisions without being forced into additional debt.
“Financial wellness is more than just income. It is about how much control you have over your finances, how resilient you are to absorb those shocks when they come, how you are progressing towards achieving your goals, and having that freedom of choice,” Kauhondamwa said.
She maintained that employers needed to address the financial pressures created by their own remuneration policies, payroll systems and employee benefits rather than placing responsibility for financial wellness entirely on workers.