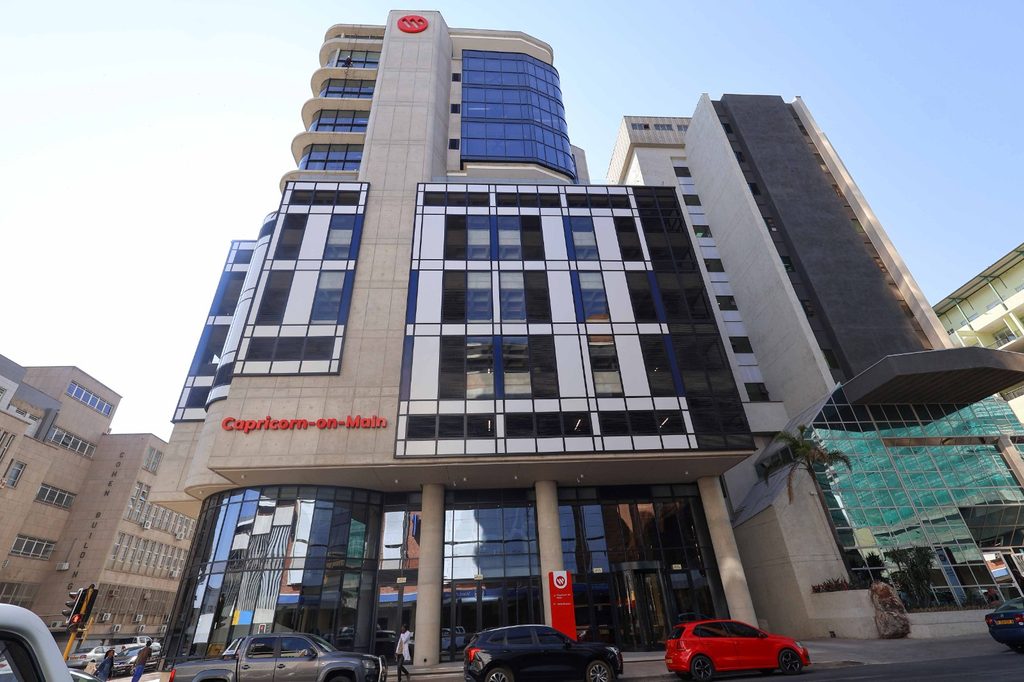
GCR Ratings has affirmed Capricorn Group Limited’s Namibian long-term issuer rating at AA(NA) and Bank Windhoek Limited’s at AA+(NA), with Stable outlooks, citing their strong domestic market positions, sound capitalisation and adequate liquidity.
Capricorn’s Namibian short-term issuer rating was maintained at A1+(NA), while Bank Windhoek retained its A1+(NA) short-term rating and South African long-term issuer rating of A+(ZA).
“The affirmed ratings on Capricorn Group Limited and its core banking subsidiary, Bank Windhoek Limited, reflect the entrenched market position of the Namibian franchise, sound capitalisation and adequate liquidity,” GCR said.
The ratings agency said these strengths were partly offset by Capricorn’s reliance on institutional deposits and weaker financial performance at its Botswana subsidiary, Bank Gaborone Limited, which continues to face pressure from the country’s credit cycle.
Bank Windhoek remains Capricorn’s largest operating subsidiary, accounting for more than 75% of Group assets and earnings and holding a 31.5% share of Namibia’s lending market.
Capricorn’s other financial services businesses also maintain significant domestic market positions, with Capricorn Asset Management holding about 40.2% of Namibia’s unit trust market and Entrepo Finance accounting for about 28% of the term-lending portfolio.
GCR said Capricorn’s core capital ratio is expected to remain between 17% and 18% over the next 12 to 18 months, supported by internal capital thresholds and a dividend payout ratio of between 30% and 40%.
Bank Windhoek reported a Tier 1 capital ratio of 18.6%, up from 17.5% in 2025, while its leverage capital ratio stood at 12%.
The bank also maintained liquidity above regulatory requirements, with its liquidity coverage ratio at 216.3% and net stable funding ratio at 123.4%.
GCR expects Capricorn’s return on equity to remain towards the lower end of the 14.5% to 17% range over the next 18 months, supported by conservative loan origination and recurring income despite continued challenges in Botswana.
Bank Gaborone remains the main pressure point for the Group, with its share of Botswana’s advances market declining to 7.9%, while its gross non-performing loan (NPL) ratio exceeded 13%.
The deterioration in Botswana contributed to Capricorn’s Group-level gross NPL ratio increasing to 5.5% from 4.7%, while its credit loss ratio rose to 0.9% from 0.6%.
Bank Windhoek’s asset quality remained comparatively resilient, with its gross NPL ratio improving marginally to 3.9% from 4.0%.
“We do not expect material deterioration in Group asset quality over the next 18 months, given Capricorn’s well-developed risk management framework. However, a credit loss ratio above 100bps could exert negative rating pressure,” GCR said.
The ratings agency expects Capricorn to maintain its competitive position, resilient asset quality and sound funding and liquidity profile over the next 12 to 18 months, while Bank Gaborone’s asset quality and earnings are expected to stabilise during the 2027 financial year.
GCR said upward rating pressure could emerge if Capricorn strengthens its competitive position, particularly in Botswana, while maintaining or improving capitalisation.
Downward pressure could arise if Bank Gaborone’s asset quality and earnings fail to stabilise, Capricorn’s credit loss ratio rises above 100 basis points or the Group makes limited progress in reducing its concentration of institutional deposits.