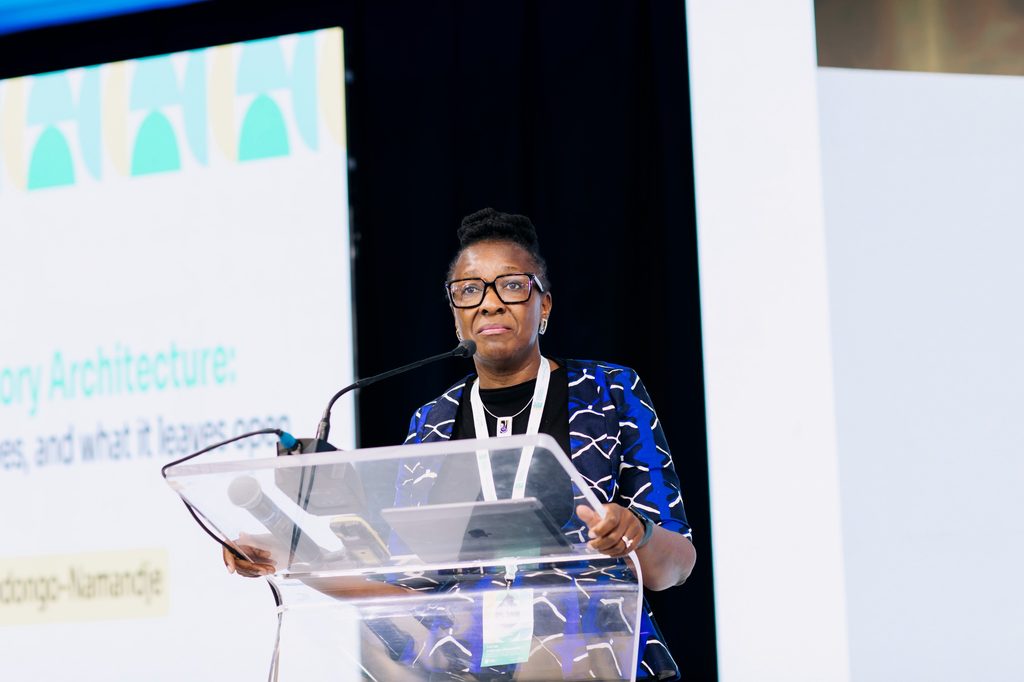
The Namibia Financial Institutions Supervisory Authority (NAMFISA) is considering further changes to pension fund investment regulations, including investment commitment periods, concentration limits and investment structures, to accommodate developments in investment markets while protecting retirement savings.
NAMFISA General Manager for Pension Funds and Societies Lovisa Indongo-Namandje said the regulatory framework needed to remain responsive to local market conditions and developments in institutional investment.
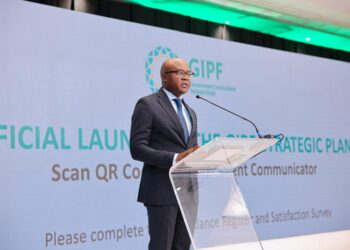
Speaking at the Government Institutions Pension Fund (GIPF) Pension and Investment Symposium in Windhoek on Wednesday, Indongo-Namandje said the regulator had to balance the protection of pension fund members and beneficiaries with the need to facilitate investment in Namibia’s economy.
“I am not a provider of capital. But in doing so, it is important that a regulator monitors their environment, and that the regulator remains adaptive to local circumstances, and that we evolve with the market and in such evolution, that we are out and cooperate with industry closely,” she said.
Indongo-Namandje said Namibia’s pension fund investment framework had undergone significant changes since 1994, when the country began establishing permissible asset classes and investment limits.
At the time, the domestic financial market was less developed, and the regulatory framework was partly intended to direct institutional capital towards local companies.
She said domestic investment allocations had since increased from less than 10% of pension fund assets in 1994 to more than 45%, while regulations had also introduced provisions allowing investment in unlisted assets.
“We went from having less than 10% of our assets invested in the domestic economy. We now are over 45% of that allocation domestic. We used to recognise true listed companies unlimited as a percentage if they were listed on the Namibian Stock Exchange. We came from a development where there were no assets dedicated to unlisted investments. We now have a provision of up to 3.5%,” Indongo-Namandje said.
She stressed that strong governance remained essential in determining how much flexibility could be introduced into the investment framework, particularly as pension funds considered more complex and alternative investments.
Under the Financial Institutions and Markets Act (FIMA), the governance framework for retirement funds addresses board competencies, the separation of responsibilities between funds and service providers, risk management and transparent investment decision-making.
“But that balance rests on one key foundation. That key foundation is governance. Not only governance from the investor side, which will always be the fund, but also governance of the investment company, for the underlying investment companies,” she said.
Indongo-Namandje said pension fund trustees were required to maintain clear investment policy statements, establish appropriate asset allocation strategies and regularly review investment decisions.
She also emphasised the need to separate the responsibilities of pension funds from those of investment managers, auditors and other service providers.
However, she acknowledged that regulation alone could not address all the constraints affecting domestic investment, including shortages of technical expertise, limited investment opportunities and gaps in the broader institutional investment environment.
“There are aspects that the regulation we cannot address. Regulation cannot fill the expertise and experience gap. Regulation cannot build a comprehensive ecosystem, whether it’s policy-wise or the development of adequate services for the industry. Also, regulation cannot improve the quantity of investments that are available in the market,” Indongo-Namandje said.
She called for greater cooperation among pension funds, investment managers, government and development partners to address these challenges.
Indongo-Namandje said NAMFISA last adjusted the investment regulatory framework in 2018 and had since consulted industry stakeholders on further amendments, with a draft awaiting promulgation.
The proposed amendments cover additional asset classes, the classification of property and infrastructure investments, recognition of multinational investments, foreign unlisted investments and co-investment arrangements.
She said further discussions were necessary to determine whether the existing framework adequately accommodated the changing nature of alternative investments.
Among the issues under consideration is the current 24-month investment commitment period, which she questioned in light of the longer investment horizons associated with many alternative assets.
Indongo-Namandje also raised concerns about concentration limits restricting the proportion of a pension fund’s assets that can be committed to a single investment, particularly for smaller funds with limited asset bases.
Other issues included the number of investment managers subject to regulatory oversight, whether existing requirements remained appropriate and the possibility of allowing alternative investment vehicle structures.
She said the industry also needed to develop greater expertise in assessing the liquidity and valuation of alternative investments, particularly as existing investments matured and reached their exit stages.
The regulatory considerations come as Namibia’s institutional investment sector faces growing calls to mobilise domestic savings for infrastructure development, business financing and broader economic growth.