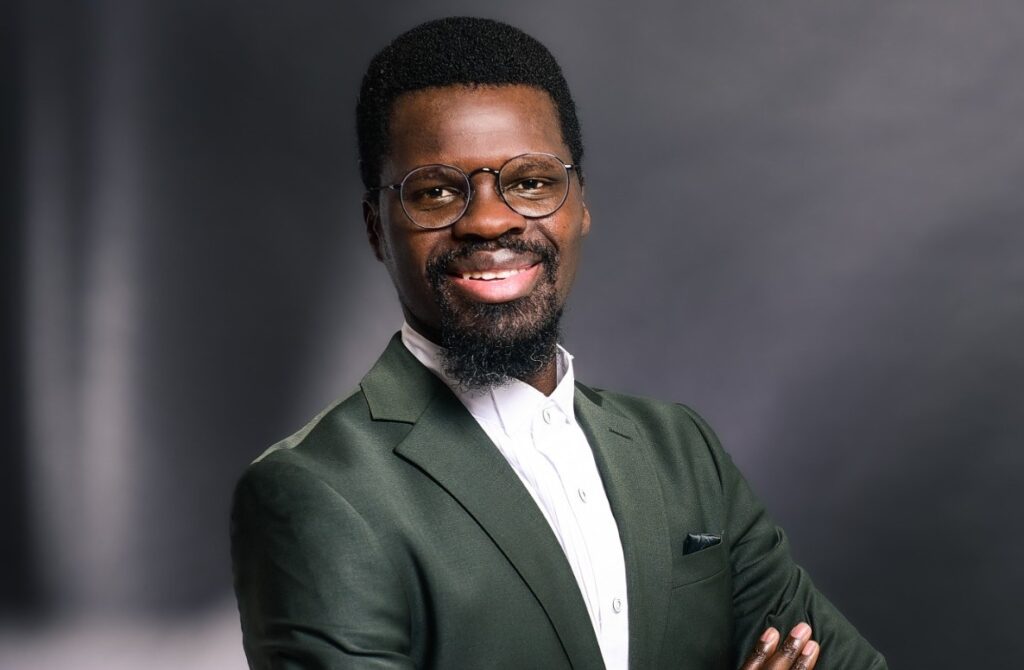
By Erastus Kalenga Hamunjela
Microlending debt in Namibia is growing faster than pensions and unit trusts. According to NAMFISA’s latest Quarterly Statistical Report, the microlending loan book grew by 19.3% over the year to N$9.3 billion as at 30 June 2026.
Over the same period, retirement fund investments grew by 15.6% and unit trust assets by 14.4%.
The gap is even wider when you look at where the growth comes from. Most of the increase in pensions and unit trusts came from market returns, not from people putting in more money. The growth in microlending comes from people taking on debt.
It is also growing much faster than bank lending. Credit extended to households by banks grew by 4.5% over the year to N$72.3 billion. Microlending grew more than four times as fast.
Most microlending debt is term lending. These are longer loans repaid in monthly instalments, often deducted straight from salaries.
Term loans grew to N$8.6 billion and make up 92.3% of the microlending loan book. Payday loans, which are repaid on the borrower’s next payday, grew to N$716.8 million.
The loans are also getting bigger. The average term loan rose 13.1% during the quarter to N$28,973, and the average payday loan rose 7.4% to N$4,329. Microlenders had 274,845 clients at the end of June, 13.9% more than a year ago.
The report counts clients rather than individuals, so a person with two lenders is counted twice.
New lending is shifting towards payday loans. Payday lenders disbursed N$739.9 million during the quarter, 20.7% more than a year ago, and issued 170,902 loans in three months. Term lending disbursements, by contrast, fell 63.5% year-on-year.
Payday loans now make up 69% of all new microlending. That is a large number of people borrowing small amounts to reach month-end.
The quarterly figures need some caution. The loan book jumped 27.0% in the quarter, but total disbursements were N$1.1 billion, still 29.4% lower than a year ago.
The report does not explain why the loan book grew so much faster than new lending. The annual trend is clearer, and it points the same way. Microlending debt is growing faster than savings.
A small number of lenders dominate the market. Express Credit Cash Advance holds about 67.8% of the payday loan book. In term lending, Letshego Micro Financial Services holds 28.7%, Entrepo Finance 26.7% and Old Mutual Finance 22.7%.
On the savings side, the sector as a whole is in good shape. Namibia’s non-bank financial sector held N$577.2 billion in assets, up 15.1% over the year.
Retirement funds hold N$316.9 billion, and the Government Institutions Pension Fund alone holds 70.1% of that. The industry’s funding level is 101.2%, meaning funds hold enough to meet what they owe members.
Unit trusts hold N$128.4 billion. But more than half of that money, 53.9%, sits in money market instruments, and only 7.8% is invested offshore. Households hold just 23.9% of unit trust assets.
Companies hold 39.0%. So much of the unit trust money is not household savings at all, and much of what is sits in cash-like investments.
Money market funds have a clear role. They are the right place for an emergency fund. But they are not built to grow wealth over ten or twenty years.
The link between these numbers is that, people without an emergency fund borrow when something unexpected happens. Every dollar that goes toward a loan repayment is a dollar that cannot be saved.
That is what keeps the cycle going.
Breaking it starts small. Build an emergency fund first, even N$200 a month, and keep it in a money market fund. Before taking any loan, look at the total you will repay, not just the monthly instalment.
Once your emergency fund is in place, put long-term money into growth investments that can beat inflation.
The sector numbers look strong. But microlending debt is growing faster than the country’s pensions and unit trusts. The question is which side of that trend you are on.
*Erastus Kalenga Hamunjela is a Namibian investment researcher and financial markets commentator with a strong focus on capital markets, investment literacy and data-driven financial education. For educational sessions, business consultations and collaborations: erastuskalengier@gmail.com