Thursday, October 22, 2026
Subscribe
The Brief | Namibia's Leading Business & Financial News
  • Home
  • Companies
    • Finance
    • Agriculture
    • Technology
    • Property
    • Trade
    • Tourism
  • Business & Economy
  • E-PAPERreader
  • Mining & Energy
  • Opinions
    • Analysis
    • Columnists
  • Africa
No Result
View All Result
The Brief | Namibia's Leading Business & Financial News
Subscribe
No Result
View All Result
Home Companies Finance

Banks warn low incomes are driving Namibians deeper into debt

by reporter
September 11, 2026
in Finance
11
A A

Low incomes and rising living costs are pushing Namibian households deeper into debt, with some increasingly relying on borrowing to meet basic expenses, the Bankers Association of Namibia (BAN) has warned.

BAN Chief Executive Officer Dantagos Jimmy said Namibia is facing an “income crisis”, with median monthly income estimated at around N$4,000, leaving many households with insufficient income to cover their living costs.

She said the resulting financial pressure is contributing to short-term borrowing, refinancing and loan stacking, where consumers take out multiple loans to meet their financial obligations.

“Namibia’s aggregate household debt position is currently contained, but there are pockets of significant household financial distress. The problem is driven by the interaction of income pressure, the cost of living, short-term borrowing, refinancing, loan stacking and insufficient financial buffers,” Jimmy said.

“This goes back to the fact that what we really have is an income crisis. Our income is not keeping up with what our salaries are expected to maintain.”

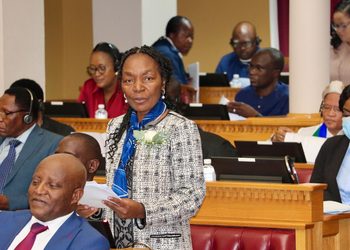
Jimmy was presenting to the Parliamentary Standing Committee on Economy and Industry, Public Administration and Planning as part of stakeholder engagements on household debt and lending practices.

BAN said private-sector credit extension has been trending downwards, arguing that the current household debt pressures are not being driven by banks aggressively expanding credit.

Jimmy said civil servants are particularly exposed to borrowing because their stable employment, predictable salaries and payroll-linked repayment mechanisms make them attractive to lenders.

She warned that these advantages could contribute to over-indebtedness when borrowers accumulate multiple loans.

“They have stable incomes and generally offer lenders predictable salaries, relatively stable employment, established payroll systems, lower collection risk and certainty, as well as the ability to use payroll-linked repayment mechanisms,” Jimmy said.

“This should have been something positive if it was being used in the way it was supposed to be used.”

BAN, however, defended the payroll deduction code system, arguing that it facilitates lending but is not the underlying cause of over-indebtedness.

The association called for reforms that would provide greater visibility of borrowers’ total deductions, protect residual income and strengthen affordability assessments.

It also proposed integrating deduction information with credit bureau data and improving transparency for borrowers to reduce the risk of consumers accumulating unsustainable levels of debt.

On borrowing costs, Jimmy said lending rates are influenced by the Bank of Namibia’s repo rate of 6.75%, the prime lending rate of 10.25% and the individual risk profile of borrowers.

Civil servants may qualify for lower rates because stable employment, predictable income and payroll deductions generally make them lower-risk borrowers.

“As we have said, we price off the monetary policy set by the Bank of Namibia. But the answer should be based on economic factors and not political considerations,” Jimmy said.

“A civil servant may represent a relatively lower credit risk because of stable employment, predictable income and payroll deductions. However, the lending rate also reflects funding costs, credit risk, capital requirements and liquidity costs.”

BAN rejected calls for arbitrary interest rate caps, arguing that borrowers have different risk profiles and that lending costs should reflect economic and risk factors.

The association instead supports an industry-wide consumer pricing transparency framework aimed at making the cost of borrowing clearer to consumers.

Jimmy also acknowledged weaknesses in Namibia’s consumer credit regulatory framework, with credit activities falling under different regulators, including the Bank of Namibia and the Namibia Financial Institutions Supervisory Authority (Namfisa).

BAN said the fragmented regulatory environment could create information gaps and opportunities for regulatory arbitrage.

author avatar
reporter
See Full Bio
Previous Post

Oryx portfolio value tops N$5bn as revenue rises 17.8%

Next Post

What if Namibian brands were built to be bigger than Namibia?

Must Read

Woman standing with papers at a formal meeting, speaking to colleagues seated around a conference desk.
Finance

Govt seeks N$700m budget increase

October 22, 2026
NamRA collects N$70 billion in gross revenue by December 2025
Finance

NamRA collects N$42.4bn in six months, reaching 51.4% of annual target

October 22, 2026
NPC reports 48% execution of N$11.8bn development budget
Finance

Shafudah to table Mid-Term Budget Review on Thursday

October 20, 2026
Namibia records second-lowest IMF debt in Africa at N$378.1m
Finance

IMF projects Namibia’s current account deficit to widen to 16.9% of GDP

October 19, 2026
Portrait of a smiling man in a blue shirt and navy blazer in a modern office with plants nearby.
Finance

Bank Windhoek disburses N$147m in sustainable loans, targets N$300m

October 19, 2026
A hand holding a salary slip labeled 'SALARY SLIP' outdoors with apartment buildings in the background
Finance

Low pay and salary delays push workers into debt

October 16, 2026
Load More

Related News

Passenger traffic at Namibian airports falls in May

Namibia’s passenger volumes dip in June but remain above 2024 levels

August 15, 2025
Namibia posts N$856m trade surplus, led by China, Botswana and Zambia

Namibia records N$9.8 billion in intra-Africa trade in January

March 10, 2026
Namibia’s rental demand remains weak: FNB

Namibia’s rental demand remains weak: FNB

November 29, 2021

Browse by Category

  • Africa
  • Agriculture
  • Analysis
  • Business & Economy
  • Columnists
  • Companies
  • e-edition
  • Finance
  • Finance
  • Fisheries
  • Green Hydrogen
  • Health
  • Investing
  • Latest
  • Market
  • Mining & Energy
  • Namibia
  • namibia
  • News
  • Opinions
  • Property
  • Retail
  • Technology
  • Tourism
  • Trade
The Brief | Namibia's Leading Business & Financial News

The Brief is Namibia's leading daily business, finance and economic news publication.

CATEGORIES

  • Business & Economy
  • Companies
    • Agriculture
    • Finance
    • Fisheries
    • Health
    • Property
    • Retail
    • Technology
    • Tourism
    • Trade
  • e-edition
  • Finance
  • Green Hydrogen
  • Investing
  • Latest
  • Market
  • Mining & Energy
  • namibia
  • News
    • Africa
    • Namibia
  • Opinions
    • Analysis
    • Columnists

CONTACT US

Cell: +264814612969

Email: newsdesk@thebrief.com.na

© 2026 The Brief | All Rights Reserved. Namibian Business News, Current Affairs, Analysis and Commentary

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Home
  • Companies
  • Mining & Energy
  • Business & Economy
  • Opinions
    • Analysis
    • Columnists
  • Africa

© 2026 The Brief | All Rights Reserved. Namibian Business News, Current Affairs, Analysis and Commentary

This website uses cookies. By continuing to use this website you are giving consent to cookies being used. Visit our Privacy and Cookie Policy.