The Agricultural Bank of Namibia (Agribank) is moving to diversify its loan portfolio beyond traditional livestock and land-based farming to reduce its exposure to drought, animal diseases and other environmental risks that continue to affect farmers’ ability to repay loans.
Agribank Chief Executive Officer Robert Eiman said the bank was deliberately targeting agricultural projects less dependent on weather conditions, including controlled-environment farming and crop production, as part of efforts to strengthen its financial sustainability and contain the deterioration of its loan book.
“This is why the bank is now deliberately looking at also diversifying its portfolio, to actively go after projects that are not necessarily linked to weather,” Eiman said.
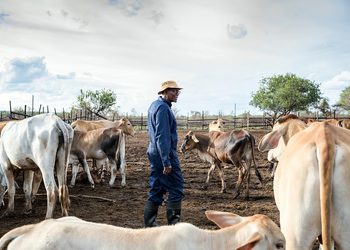
He said a significant portion of Agribank’s loan portfolio remained concentrated in traditional agricultural activities, exposing the institution to recurring droughts, livestock diseases and other disruptions affecting agricultural production and farmers’ incomes.
The diversification strategy comes as the bank grapples with non-performing loans and repayment arrears, with the ongoing foot-and-mouth disease (FMD) outbreak placing additional pressure on livestock farmers.
Eiman said Agribank was assessing the financial impact of the outbreak on its borrowers and considering repayment relief measures, including extending instalment due dates and reviewing penalty interest.
“We are trying to avoid a blanket approach and look at it on a case-by-case basis because people are impacted differently and we don’t know the window of the impact,” he said.
He said affected farmers could be granted additional time to meet their repayment obligations, depending on the severity of the disruption to their operations.
“We might have to look at pushing those instalments and make sure that it’s not burdened by penalty interests and the likes,” Eiman said.
The bank is engaging directly with affected customers to assess their financial circumstances and determine appropriate interventions rather than introducing a uniform repayment relief arrangement.
Eiman acknowledged that Agribank was already facing challenges with non-performing loans and arrears before the FMD outbreak, making it necessary to address the underlying causes of repayment difficulties.
“It’s not simply that they don’t want to pay. There are other factors as well. And this is trying to understand those factors to see what the remedies are that you can put in place,” he said.
He warned that continued deterioration in loan repayments could undermine the bank’s ability to provide financing to the agricultural sector.
“We have to put brakes on the deterioration of the loan. The bank can only fulfil its development mandate if the bank is sustainable,” Eiman said.
He said the bank’s immediate priority was to work with borrowers experiencing financial difficulties to find repayment solutions before considering legal action or the auctioning of assets.
“As a bank, our priority is not auctions and our priority is not taking customers to court. That is the last thing that we want to do,” he said.
Eiman urged farmers struggling to service their loans to approach Agribank and engage with the institution on possible repayment arrangements.
“We want to be in a situation where the customer and the bank meet each other halfway, and that is really the message. Let us meet each other halfway,” he said.
He said diversifying Agribank’s lending portfolio towards agricultural activities less vulnerable to weather-related disruptions would help spread lending risks and improve the bank’s overall loan performance.
The strategy is intended to reduce the concentration of lending in traditional farming activities while supporting Agribank’s ability to continue financing agricultural development despite recurring environmental and disease-related shocks.